How Automated KYC Reduces Friction in Fraud Detection


Financial institutions and digital businesses are tasked with two seemingly antithetical obligations: protecting their customers’ data and providing a seamless user experience.
Why antithetical? A handful of manual identity verification measures—multi-factor authentication, one-time passwords, and delivering paperwork in person—are widely viewed as burdens by the customer.
This can result in greater friction in onboarding and transaction processes—and the diminished conversions, reduced retention rates, and increased drop-offs that may arrive with it.
This is where automated know your customer (KYC) serves as an increasingly attractive solution. In this article, we’ll examine how automating KYC processes benefits businesses and customers in the battle against fraudulent activity.
What is KYC?
Performed to prevent identity theft, money laundering, and financial crimes before they occur, regulated industries—such as banking, alcohol, travel, tourism, and gaming—are legally required to comply with KYC regulations. That said, nearly every business may profit from adhering to KYC guidelines because of the confidence it can foster and the financial protection it offers.
How do KYC regulations relate to anti-money laundering (AML) laws?
The concept of KYC fraud detection dates back to the Bank Secrecy Act (BSA) in the 1970s—a set of regulations and laws developed to counter the risk of financial terrorism, money laundering, and other illegal activities.
Anti-money laundering (AML) laws stemmed from this. KYC compliance is an imperative component of these laws. To remain compliant, financial organizations and additional industries must execute ongoing monitoring and flag (and report) any suspicious activity.
Drawbacks of traditional KYC methods
Traditional KYC methods—such as providing an institution with physical documents like a utility bill—may have been acceptable before the digital age. In our accelerated era, however? Not so much.
The primary pitfalls of traditional KYC methods come down to:
- Decreased customer satisfaction: A recent survey reveals that 82% of customers expect a smooth and simple digital experience. Manual KYC measurements interfere with this. Largely deemed as a time-consuming hindrance, it can delay onboarding and negatively affect a customer’s perception. As digital banks become increasingly popular, this has significant implications in the financial services sector.
- Increased risks: Manual KYC methods (and the data entry required) are subject to human errors and inconsistencies, which may render financial organizations and other businesses vulnerable to fraud and compliance missteps. Further, organizations that store physical documents may place data security and privacy at risk; breaches could be fatal to an institution’s reputation and ultimate success.
- Elevated costs: Traditional KYC procedures naturally call for human labor. This can be tremendously costly for organizations requiring large volumes of identity verifications while handling KYC protocols. Moreover, failing to comply with KYC regulations—which have become progressively more rigorous and nuanced amid growing financial crimes—comes with hefty fines: in 2021 alone, several US financial organizations accrued $2.7 billion in penalties for not meeting KYC and AML regulations.
- Reduced scalability: Relying on manual KYC methods impacts an organization’s capacity to scale. This can unnecessarily stunt a company’s growth, as automated KYC processes are readily available—a topic we’ll turn to next.
The role of automated KYC in reducing friction
In sum, using technology such as AI to verify a legitimate customer’s identity can significantly curb friction in onboarding and transactional processes by saving both businesses and customers time and effort. This is key across the board, especially in industries where swiftness and ease are fundamental.
Benefits of automated KYC in fraud detection
Automated KYC verification processes have a host of advantages, namely:
- Decreased operational costs: As discussed, traditional KYC methods require internal staff members to not only conduct identification processes but also remain on top of changes in KYC regulations. Automated KYC shrinks labor and other overhead costs, empowering organizations to realize their growth potential (and boost their bottom line).
- Lowered risks: Automated KYC provides perpetual monitoring in real-time. This enables institutions to spot activity that may be indicative of financial fraud (and other illicit activities) promptly and effectively.
- Enhanced customer journey: Organizations and businesses that offer timely, frictionless experiences are more likely to satisfy—and retain—customers.

KYC technologies and innovations
We’re just beginning to uncover the world of automated KYC options. To date, however, the most prevalent technologies and innovations include:
- AI/ML, which can review enormous datasets and analyze them for patterns and deviations
- Liveness detection, which can conduct facial movement evaluations to confirm a customer’s identity
- Document verification, which checks a customer’s identity through capturing, extracting, and certifying identification documents (such as a passport)
Voice biometrics, facial recognition, and behavioral biometrics are also employed.
What do companies need to know about implementing KYC procedures?
KYC is broken down into three phases for banks and other financial institutions:
- Customer identification program (CIP): CIP accounts for essential information needed for identity verification. This data is contingent upon the jurisdiction, but it typically involves verifying the customer’s name, address, date of birth, and a government-issued identification number (such as their driver’s license number).
- Customer due diligence (CDD): Simply put, CDD assesses a customer’s risk factor to an organization, primarily in terms of fraudulent schemes, all of which can undermine an institution’s financial success and reputation.
- Enhanced due diligence (EDD): EDD is the most stringent form of due diligence. Conducted with high-risk customers—such as a politically exposed person (PEP)—it helps institutions make savvy choices about onboarding customers and establish measures to manage potential risks.
- Sanctions, PEP and watchlist screening should be treated as another layer of KYC rather than identity verification itself. After establishing who a customer is, organizations may need to determine whether that person appears on applicable sanctions or law-enforcement watchlists, qualifies as a politically exposed person, or presents other risk indicators. Depending on the organization’s regulatory obligations and risk model, adverse media may also provide information relevant to customer due diligence. Importantly, a match should not automatically be treated as proof of wrongdoing. Screening systems need processes for resolving potential matches, distinguishing false positives and escalating cases for appropriate review.
How risk-based KYC works
Effective KYC does not require every customer to go through the same verification process. A risk-based approach evaluates the signals associated with each customer and interaction, then applies a level of due diligence appropriate to the risk.
For example, a customer whose identity information can be verified against trusted sources and who presents no significant risk indicators may move through onboarding with minimal additional friction. An applicant with inconsistent information, a higher-risk geography, an unusual device or other warning signals may be routed to document verification, biometric verification or another step-up check. Cases that remain uncertain can then be escalated to enhanced due diligence or manual review.
This creates a tiered KYC process rather than a single rigid verification path. Lower-risk customers can move through onboarding quickly, while higher-risk interactions receive additional scrutiny. Risk can also change after onboarding, making ongoing monitoring and re-verification important when new signals indicate that an established customer or account may warrant another look.
How can you streamline KYC implementation?
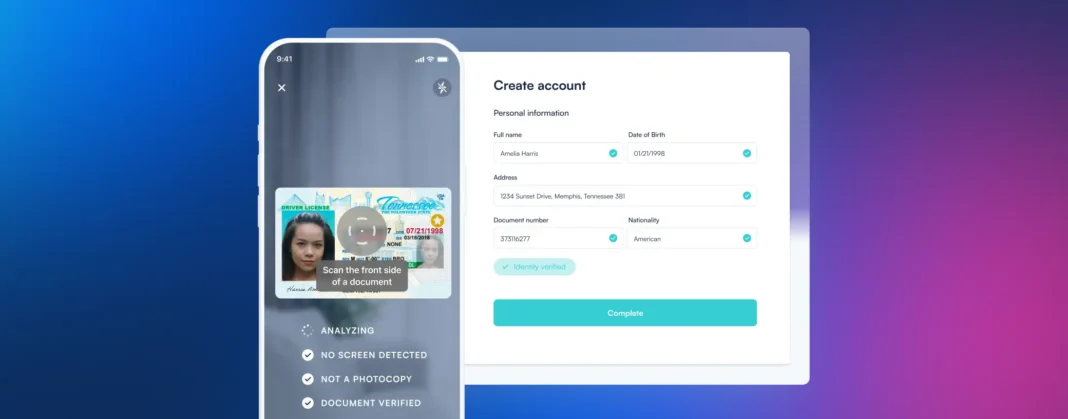
Automated, AI-powered KYC conducts the most vital elements of KYC with accuracy and speed, chiefly through:
- Document scanning
- Identification verification
- Risk assessment
Are there limitations to this? Yes.
Every case is unique, and some may be complicated. Yet, one of the beauties of AI/ML is that they are, at their crux, constantly evolving to adapt to challenges.
What types of fraud can KYC help detect?
KYC fraud is not a single type of attack. Fraudsters can use stolen information, manipulated documents, synthetic identities or legitimate accounts to disguise who is actually behind an interaction. Understanding those different attack patterns helps organizations determine which identity and risk signals they need to evaluate.
Stolen identity fraud occurs when a fraudster uses another person’s personal information or identity documents without permission to impersonate them. Strong identity verification can help determine whether the person presenting an identity is actually its legitimate owner.
Synthetic identity fraud combines real and fabricated identity information to create an identity that may appear legitimate. Rather than simply impersonating one existing person, fraudsters can combine elements from multiple sources or introduce invented information to construct a new identity. These attacks make it important to evaluate multiple signals rather than relying on a single piece of identity data.
Document fraud involves altered, counterfeit, stolen or digitally manipulated identity documents. Generative AI has made it easier to create convincing fake documents and modify legitimate ones, increasing the importance of document authenticity checks that look beyond whether an ID appears visually plausible.
Biometric spoofing and deepfakes attempt to defeat facial matching or liveness checks using photographs, video replays, face swaps, synthetic imagery or other manipulated media. Effective biometric verification therefore needs to establish both that the person matches the identity being presented and that a live person is participating in the verification.
Money mule activity presents a different challenge because the person interacting with the institution may be using their real identity. Mule accounts can be opened or used to receive, transfer or withdraw illicit funds on behalf of criminals. Detecting this activity may therefore require transaction monitoring and behavioral or contextual signals in addition to identity verification.
These examples illustrate why modern KYC fraud detection increasingly depends on multiple layers of evidence. A genuine document alone does not necessarily mean the interaction is legitimate, just as an unusual behavioral signal does not automatically prove fraud. Combining identity, document, biometric and contextual information can provide a more complete picture of risk.
Maintain an auditable record of KYC decisions. Compliance requires more than reaching the right decision. Organizations also need to understand and demonstrate how that decision was made. KYC workflows should preserve relevant verification results, risk signals, screening outcomes, escalations and manual-review actions so teams can reconstruct the reasoning behind a decision when necessary.
This becomes particularly important as automation assumes a larger role in KYC. When an automated system approves, rejects or escalates a customer, compliance teams should be able to understand the signals behind the outcome rather than relying on an unexplained pass/fail result. Clear audit trails also make it easier to investigate suspicious activity, evaluate program performance and provide evidence during regulatory examinations.
How to pick the right KYC fraud detection technology
Selecting the most effective and appropriate KYC fraud detection technology for your organization depends on your business requirements and the technology’s ability to help you scale. Additionally, you may want to analyze the technology’s user-friendliness, integration capabilities, and operational efficiencies. Microblink was designed with all of this in mind to give companies best-in-class experiences.
What signals are used in KYC fraud detection?
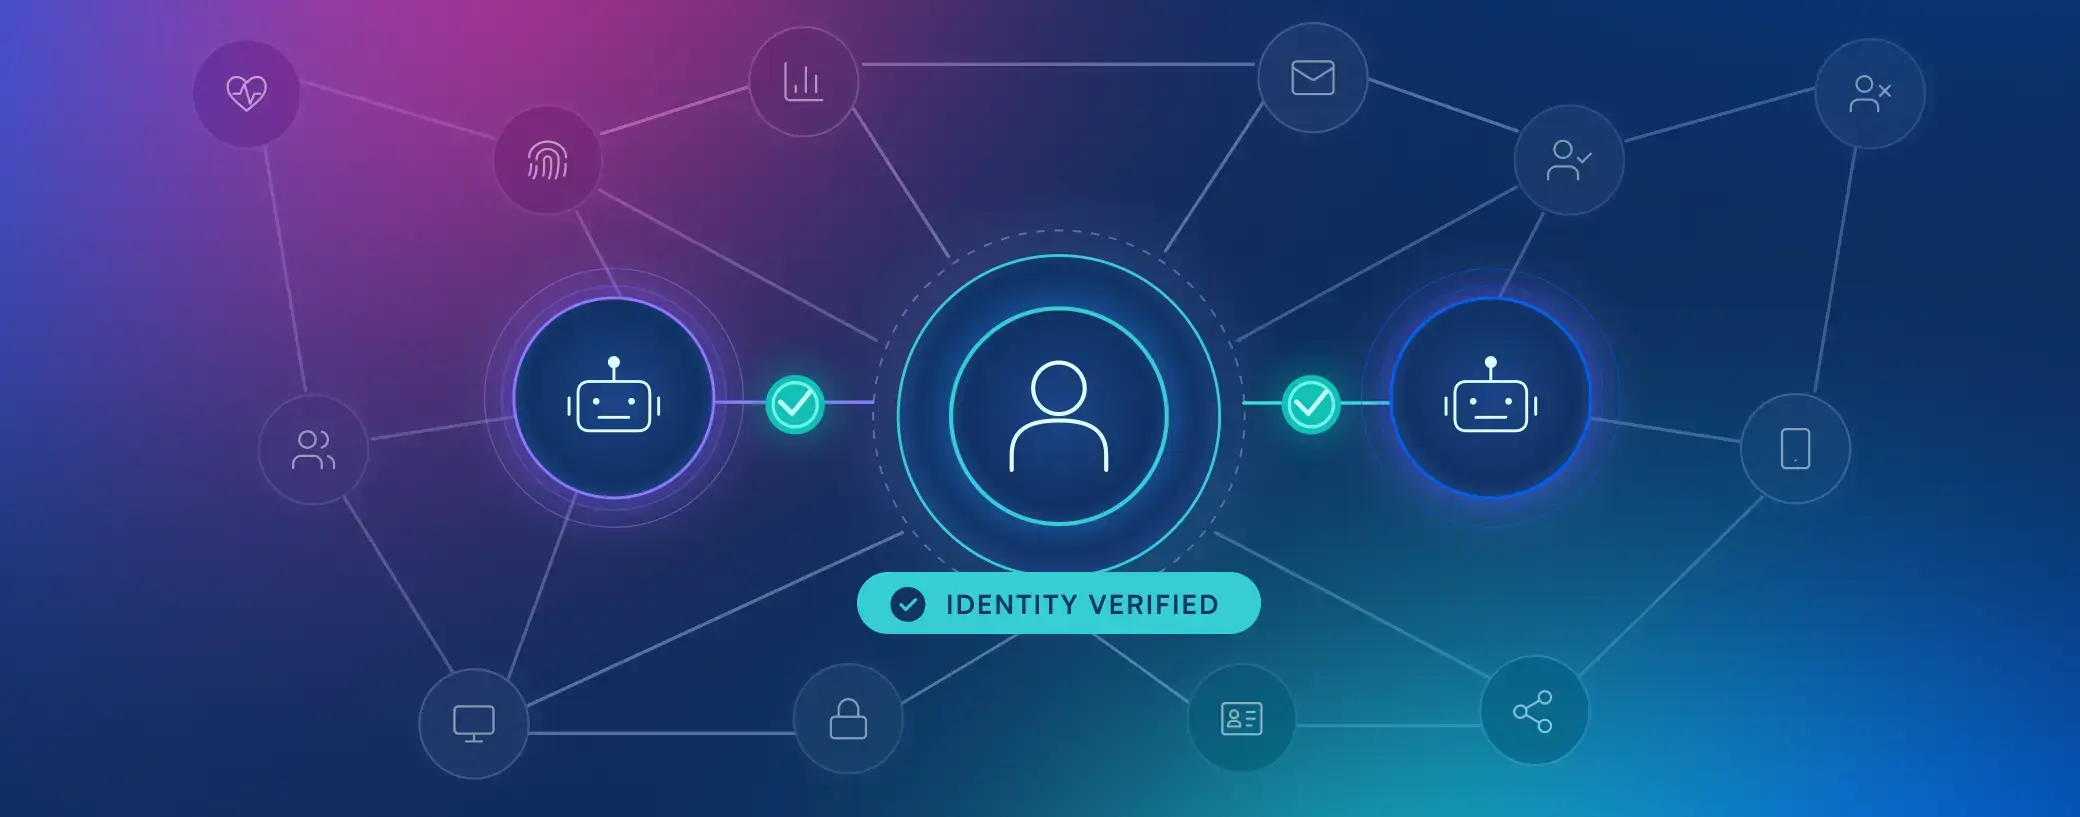
Modern KYC systems can draw on multiple types of information to determine whether an identity and interaction can be trusted. Which signals are appropriate depends on the organization, jurisdiction, product and level of risk.
Identity evidence may include government-issued documents, biometric matching and liveness detection. Organizations may also use trusted third-party data sources, such as public records or other authoritative databases, to corroborate information supplied by the customer.
Device and contextual signals can add another layer of insight. Device characteristics, IP and network information, session behavior and patterns in how a user interacts with an application can help identify anomalies that would not necessarily appear during a document check alone. For example, multiple applications associated with the same device or unusual changes in location and session behavior may warrant additional investigation when considered alongside other risk indicators.
No single signal provides a complete view of risk. Combining identity evidence with contextual, behavioral and external information allows organizations to make more informed decisions and introduce additional verification when the evidence warrants it.
How Microblink Can Help
As one of the top KYC solution providers, Microblink is at the vanguard of automated KYC. Our BlinkID helps organizations like yours guarantee that people are who they claim to be through our document scanning and verification technologies.
This could streamline customer identity verification and mitigate fraud by as much as 50%, bolstering your ever-important business relationship with your customer—and granting you the chance to exceed your potential.
Consider automating with Microblink to streamline your KYC implementation and enhance fraud detection. Take advantage of our cutting-edge technologies by trying a demo today.