Digital IDs and Wallets
Users share a mobile driver's license, national eID or wallet credential in a few taps, and fall back to document capture when needed. One integration returns one result.
Microblink's Approach to Digital ID
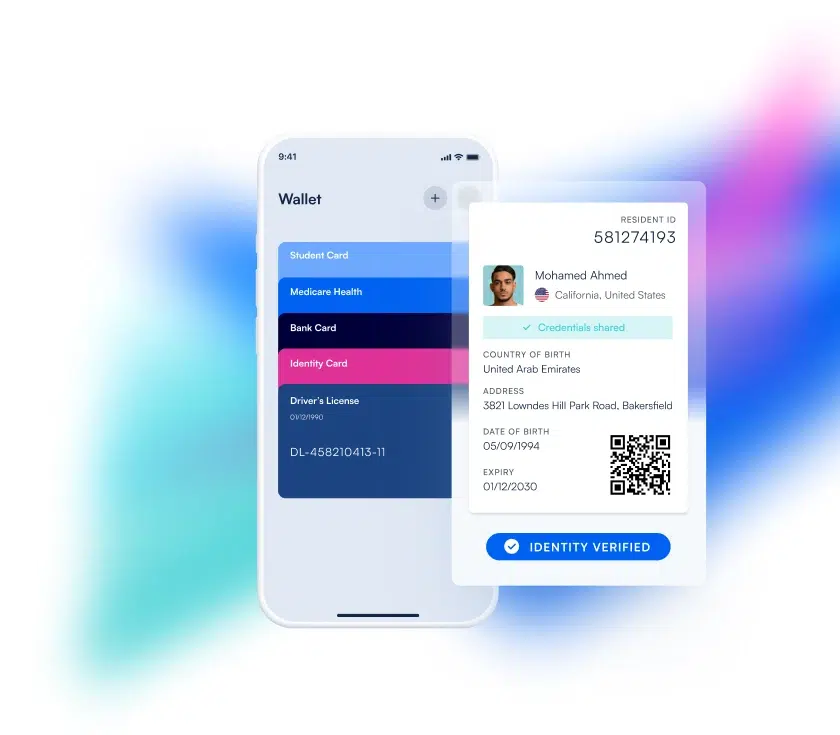
Governments, banks and wallet providers enroll users and issue credentials. Microblink verifies those credentials when users present them. Digital IDs run in the same Identity Intelligence OS workflow as document and biometric verification, so customers set rules once and accept the strongest ID each user has.
HOW IT WORKS
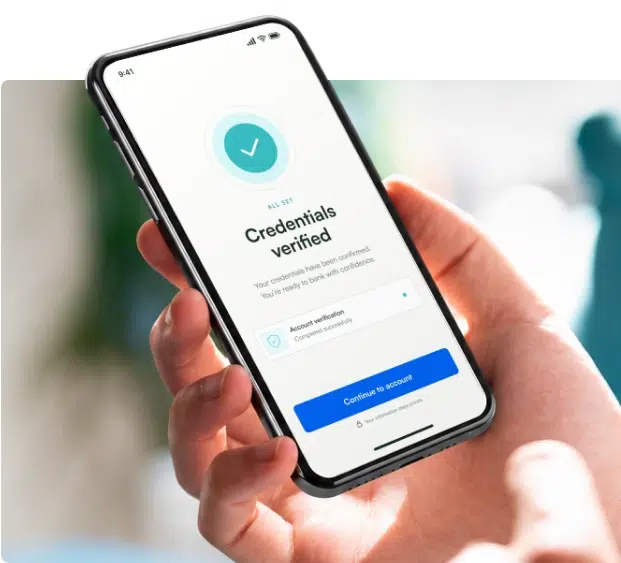
Users verify with a credential their government, bank or wallet provider has already checked. With no camera capture, more users finish verification. The hand-off adapts to the ID provider and the device: a QR code on desktop, a deep link or native wallet prompt on mobile (where the wallet supports it), or a redirect to the provider’s sign-in. Microblink builds the selection and hand-off screens for web, iOS and Android, styled to the customer’s brand.
The user begins verification in the customer’s app or site and gives consent before any data is shared.
Microblink suggests the digital IDs available in the user’s country, with document scan as an option.
The user unlocks the wallet or ID app and approves the listed data.
The user lands back in the customer’s flow, and the customer receives one result.
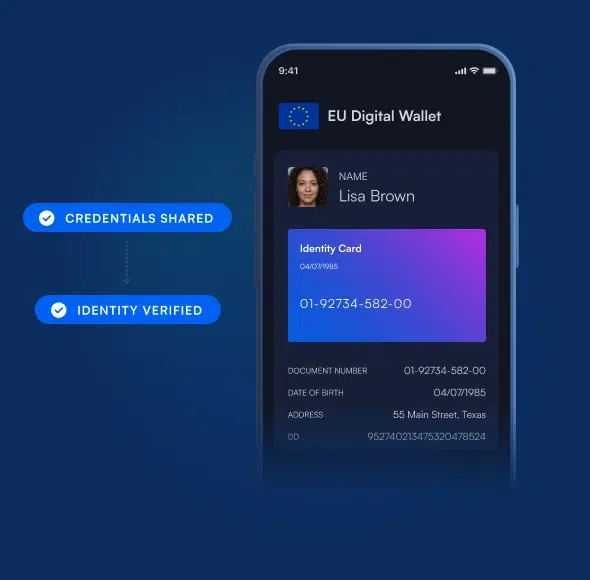
National eID apps let citizens prove identity online, and EU member states are rolling out EU Digital Identity Wallets. Users approve the share in the app their government provides. Verified attributes reach the workflow in the same format as every other ID type.
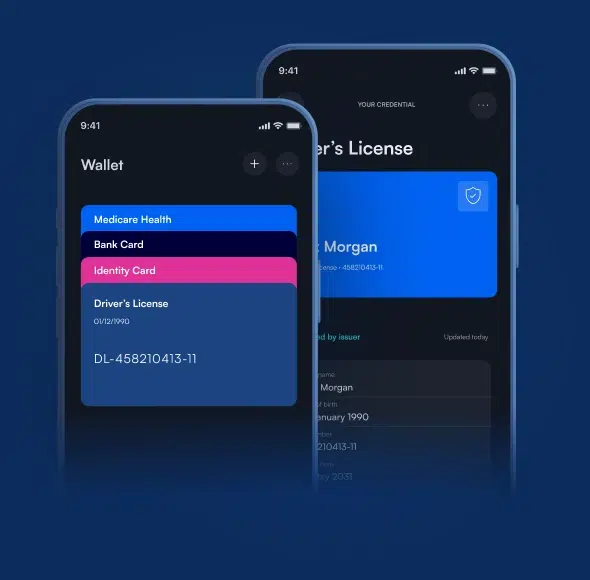
US states issue mobile driver’s licenses, and phone wallets now hold government IDs. Users share these credentials from the phone they already use, on web or in app. The issuer signs the data, and Microblink validates that signature before the workflow makes a decision. A signed credential is much harder to forge than an image of a document.
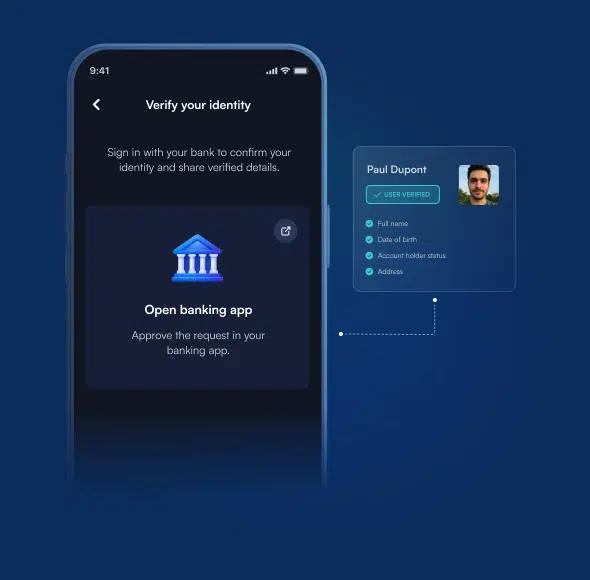
In many markets, a bank login is the everyday way to prove identity. Users sign in with their bank ID and consent to share attributes the bank verified under KYC. Every result names the scheme used, so compliance teams know what they accepted.
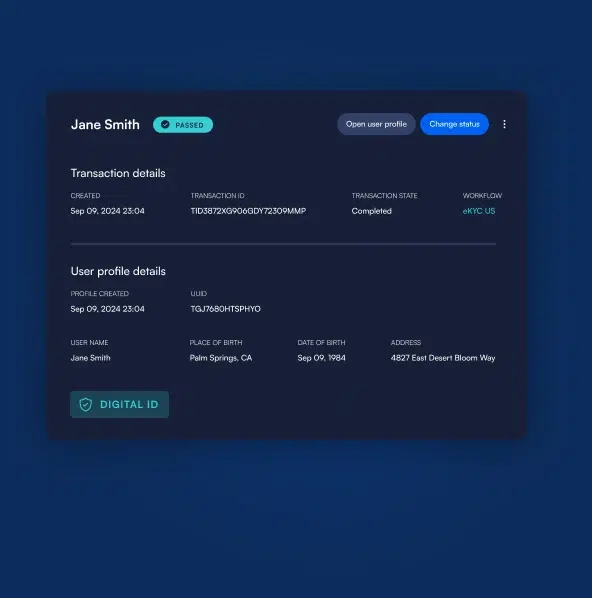
Digital ID and document checks return the same response format through API and webhooks. Each result carries the decision, normalized identity data, the method used, its assurance level and an audit trail. Fraud and risk teams review every path in the Platform dashboard.
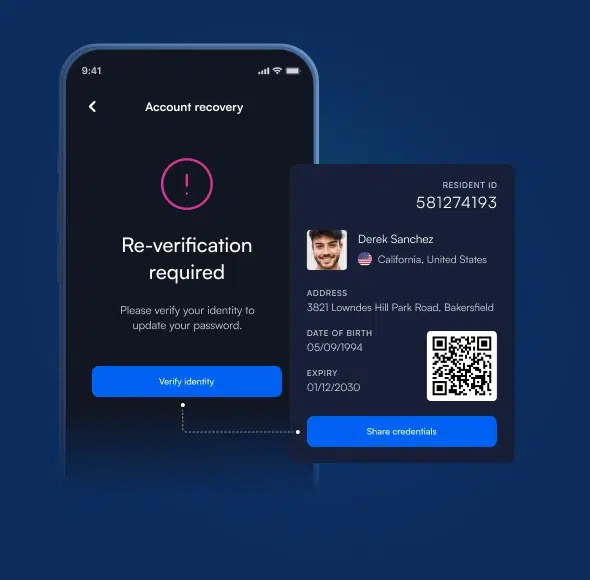
Returning users prove who they are again by sharing the same digital ID. Account recovery, high-risk account changes and periodic KYC refresh take a few taps instead of a new document scan.
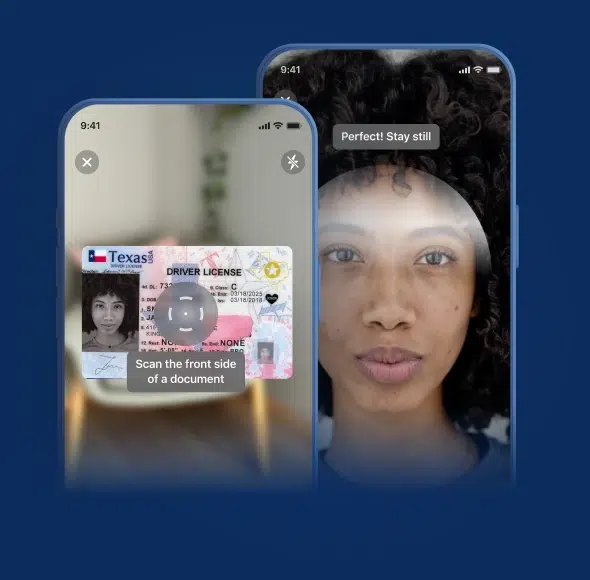
When a user has no digital ID, declines the share or the provider is unavailable, the workflow moves to physical document capture and authentication in the same session, with optional biometrics. Users without a digital ID still complete verification.
Assurance by ID type
Digital IDs differ in strength. Every result names the method and source, and the workflow decides which ID types qualify, the same way it handles document types today.
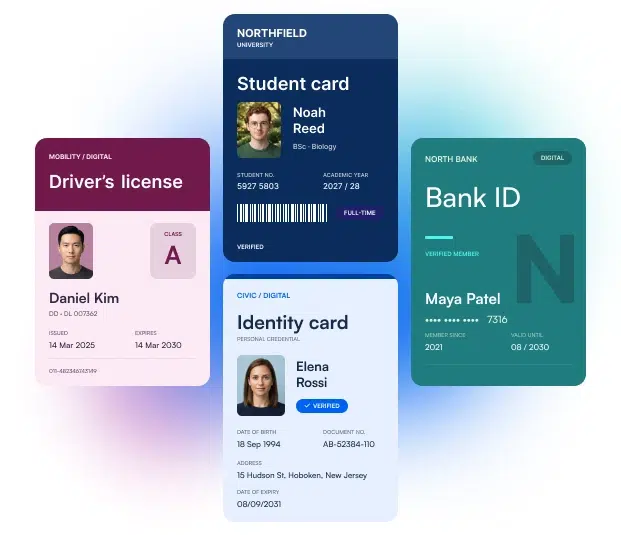
ID verification connects with biometrics, database checks, payment card checks, non-ID documents, and watchlist screening inside the Identity Intelligence OS, a continuous control layer across the entire user journey. Identity verification might start with ID documents, but trust requires a unified evaluation of all signals and behaviors that define an actor.
Explore the Identity Intelligence OSTESTIMONIALS
Microblink was very easy to integrate and allowed us to move quickly without compromising on security or compliance.
The SDK gave us a strong plug-and-play starting point, and the Microblink team was highly responsive throughout testing and rollout.
Overall, it was a very smooth experience.
— Mathieu Hartvick
Instacart
Software Engineer and Project Lead
By integrating Microblink’s technology into our platform for automotive lenders across Mexico, we’ve been able to dramatically accelerate and optimize ID verification.
We’ve achieved a 98% success rate, making the entire KYC process faster, smoother, and more reliable for our business and our customers.
— Fabián Ramírez
Latin ID
Product Owner
Banco Azteca was able to easily implement BlinkID across multiple mobile applications and use cases, whether users were trying to open a bank account or apply for a loan.
We couldn’t be more impressed with how agile and versatile it is, seamlessly integrating with our onboarding processes while delivering accurate, real-time results.
— Francisco León
Banco Azteca
IT Director
Microblink was very easy to integrate and allowed us to move quickly without compromising on security or compliance.
The SDK gave us a strong plug-and-play starting point, and the Microblink team was highly responsive throughout testing and rollout.
Overall, it was a very smooth experience.
— Mathieu Hartvick
Instacart
Software Engineer and Project Lead
By integrating Microblink’s technology into our platform for automotive lenders across Mexico, we’ve been able to dramatically accelerate and optimize ID verification.
We’ve achieved a 98% success rate, making the entire KYC process faster, smoother, and more reliable for our business and our customers.
— Fabián Ramírez
Latin ID
Product Owner
Banco Azteca was able to easily implement BlinkID across multiple mobile applications and use cases, whether users were trying to open a bank account or apply for a loan.
We couldn’t be more impressed with how agile and versatile it is, seamlessly integrating with our onboarding processes while delivering accurate, real-time results.
— Francisco León
Banco Azteca
IT Director
FAQ
Have another question?
Contact our team!
Mobile driver’s licenses, wallet-based IDs, national eIDs, EU Digital Identity Wallets and bank-based IDs. Coverage spans Europe, North America, Latin America and beyond, and keeps growing. Contact Microblink for coverage in specific markets.
Digital ID verification supports onboarding and re-verification. Returning users can share the same digital ID for account recovery, high-risk account changes and periodic KYC refresh instead of scanning a document again.
When a user has no digital ID, declines the share or the provider is unavailable, the workflow moves to physical document capture and authentication in the same session, with optional biometrics. Users without a digital ID still complete verification.
LATEST
Evaluate Microblink in your environment.

We appreciate your interest in our products and will get back to you shortly.
If you want to see our demo in action and talk about your use case, feel free to book a meeting .
If you want to see our demo in action and talk about your use case, book a meeting right now.
An email has been sent to you with full booking details.
We look forward to showcasing our solutions to you soon.

لم يقتصر دور الذكاء الاصطناعي على تسريع عمليات الاحتيال فحسب، بل جعلها نظامًا متكاملًا. فقد قمنا بتحليل ملايين التفاعلات المتعلقة بالهوية لرسم خريطة لكيفية تطور هجمات الهوية عبر المناطق وأنواع الهجمات ومستويات تعقيدها — وما يتعين على المؤسسات إعادة النظر فيه لمواكبة هذه التطورات.
اطلع على البيانات